
What is an MCS-90 endorsement and does it protect me?
The MCS-90 guarantees payment to the public, not coverage for you. What it does, what it does not, and why the difference can cost you.
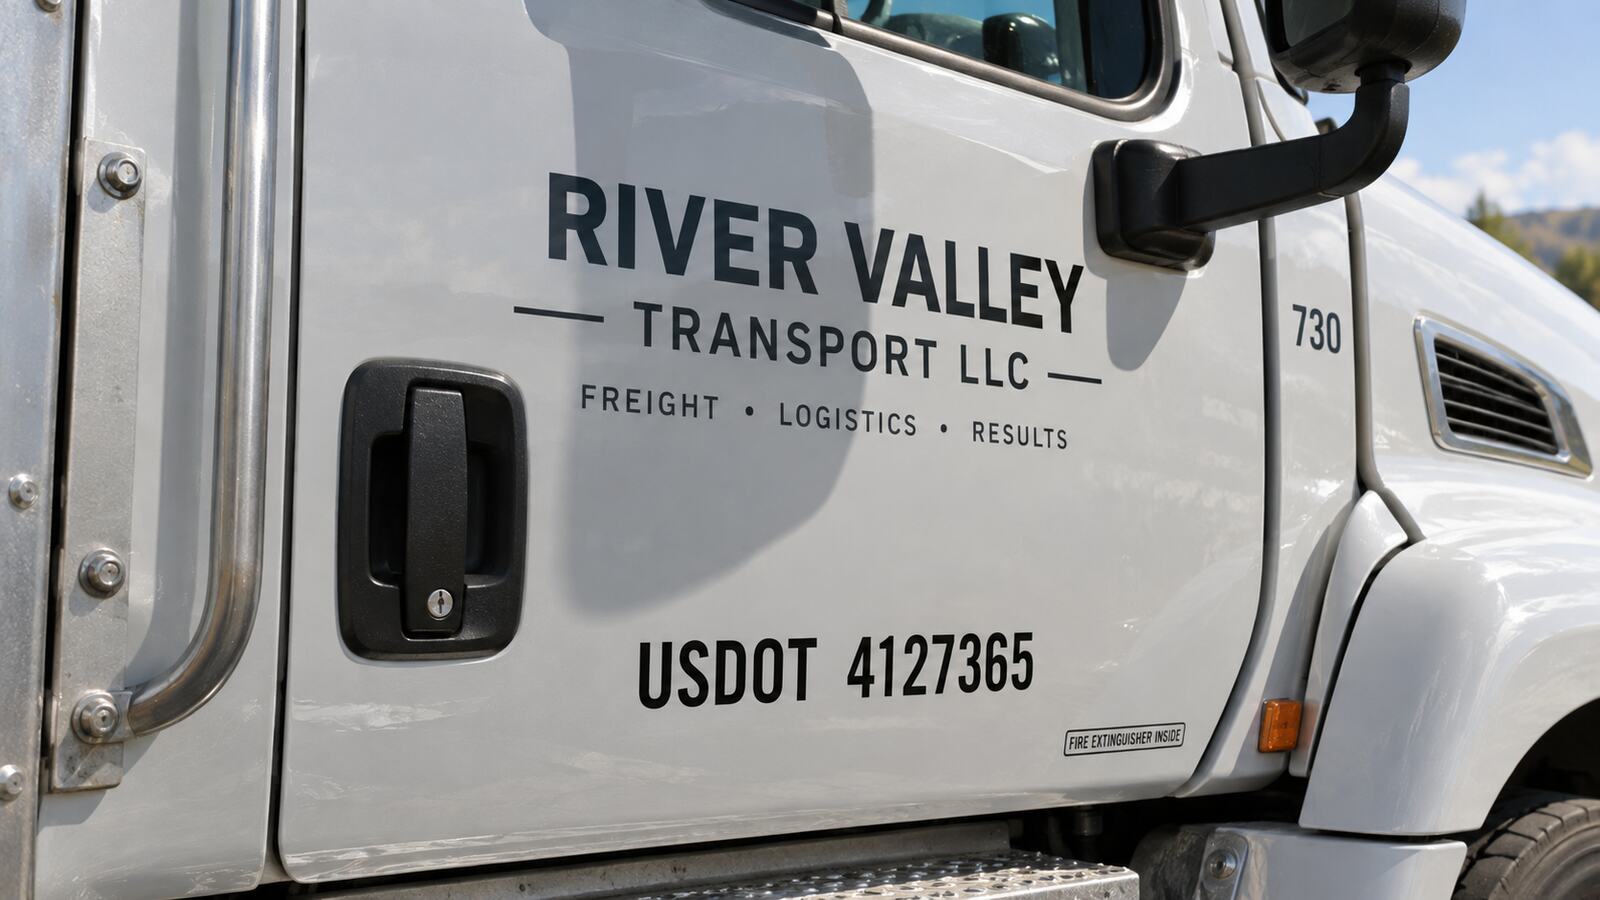
- The MCS-90 is a guarantee to the public at the federal minimum. Your real protection comes from the policy it is attached to.
- If the insurer pays under the MCS-90 for something the policy did not cover, it has the right to collect that money back from you.
- Treat the MCS-90 as a compliance document, not as protection. The protection comes from having the right coverage underneath it.
The MCS-90 does not protect you. It is a federal endorsement, an add on to your liability policy, that promises the public will be paid up to the federal minimum. If the policy would not have covered the loss, the insurer can come back to you for the money. Carriers ask for it, brokers ask for it, and most operators believe it is coverage. It is not.
What the MCS-90 endorsement actually is
The MCS-90 is a federal endorsement attached to a motor carrier's liability policy. It guarantees the insurer will pay a judgment for injury or property damage caused by the carrier's operation, up to the required minimum, even if the policy would not otherwise cover that loss. It is required by 49 CFR 387.15 for carriers under the federal financial responsibility rules. The form itself is published by the FMCSA.
The reimbursement clause people miss
If the insurer pays under the MCS-90 for something the policy did not cover, it has the right to collect that money back from you. Every dollar of it. The form says so directly. The insured agrees to reimburse the company for any payment it would not have owed under the policy except for the endorsement.
Say a carrier is operating outside the terms of its policy, for example hauling a commodity the policy excludes. The injured person may get paid, and the insurance company may then send the carrier a bill. The public is protected. The carrier is not.
What it does not do
- It does not cover damage to your own truck
- It does not cover your cargo, and it does not cover injuries to your own employees. The form excludes both
- It does not raise your policy limits beyond the federal minimum
- It does not fix a gap in the coverage underneath it
What to do with that information
Treat the MCS-90 as a compliance document, not as protection. The protection comes from having the right coverage underneath it: the right radius, the right commodities, every driver listed, every truck listed. See how filings and authority work.
- Tell your agent exactly what you haul and where, and update it when it changes
- Read the exclusions on your liability policy, especially the commodity and radius limits. Cargo has its own policy; see motor truck cargo coverage.
- Keep the driver list current. An unlisted driver is a classic reason a claim falls outside the policy
- If you add a new commodity or a new lane, call before the first load, not after. See why radius matters and keeping the driver list current.
We keep the underlying policy honest
The goal is never to need the MCS-90 to do anything. We will make sure your policy matches your real operation. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Is the MCS-90 required for intrastate hauling?
It is a federal endorsement tied to interstate authority. Texas carriers that stay inside the state have state filing requirements instead. Ask which applies to you.
Does having an MCS-90 mean I am fully insured?
No. It is a guarantee to the public at the federal minimum. Your real protection comes from the policy it is attached to.
Can the insurance company really come after me?
Yes. The right to be paid back is written into the endorsement, and insurers do use it.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.