
Why is car insurance so expensive in McAllen?
Claim costs, uninsured drivers, hail and car theft all feed a McAllen auto rate. Here is what you can change and what you cannot.
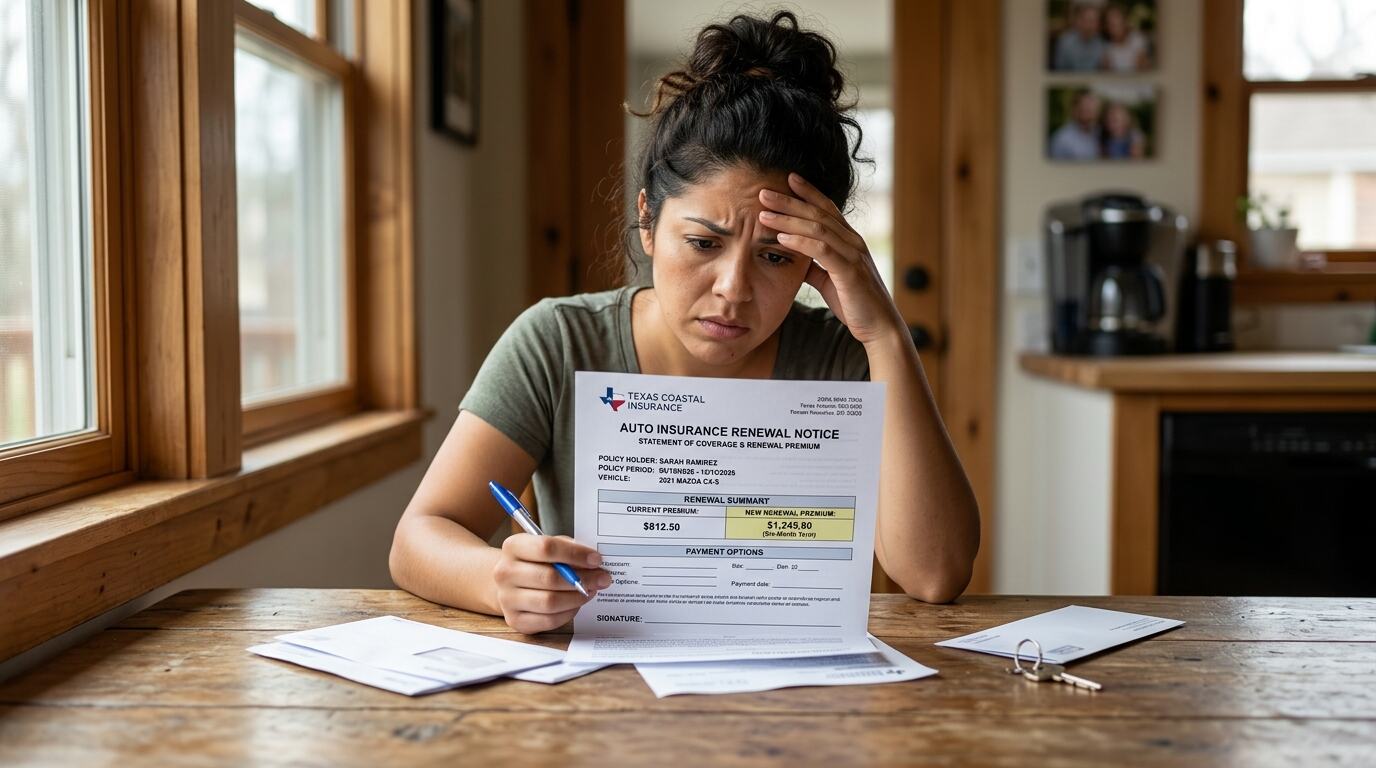
- Texas lets companies set your rate on your driving record, your ZIP code, the car, how much you drive, your prior insurance history, and a credit based insurance score.
- Letting coverage lapse is the costly mistake here, because companies weigh prior insurance heavily and a few months with no policy follows you for years.
- Compare across companies at least every two years, and after any change in your life.
Texas rates are set by ZIP code, and South Texas ZIP codes carry factors that push the premium up. A premium is the monthly bill for the coverage. Some of what drives it is out of your hands, and some is not.
Why car insurance rates are high in McAllen and South Texas
- A high share of drivers here carry no insurance. That pushes up liability and uninsured motorist costs for everyone who does pay. Liability pays other people when you cause a wreck. See why it matters here.
- Hail, which brings comprehensive claims in volume across Hidalgo and Cameron counties. Comprehensive pays for damage that is not a crash, such as hail or theft. See how hail claims work.
- Traffic on the expressway between McAllen, Pharr and Edinburg.
- Car theft in the border counties, which feeds into comprehensive pricing.
- Repair and medical costs, which have gone up faster than premiums for several years.
The rating factors you control
A rating factor is anything the company looks at to set your price. These are the ones you can move.
- Your driving record. After where you live, it is the largest one.
- Continuous coverage, meaning no gap between policies. A gap of even a month moves you into a worse rate tier at most companies.
- Your deductible, the amount you pay yourself on a claim before the policy pays.
- The car itself, since repair cost and theft rate vary a lot by model.
- How you pay. Paying in full and automatic draft usually earn a discount.
- Bundling home or renters with auto, meaning both come from one company.
The mistakes that cost the most here
Letting coverage lapse is the expensive one. A lapse is any stretch of time with no policy in force. Companies weigh prior insurance heavily, and drivers who go without for a few months pay for it for years.
If money is tight, drop down to liability rather than dropping the policy. See what a lapse costs beyond the fine.
The other one is staying put out of habit. Rates drift, and the company that priced well for you three years ago may not price well for you now. After a wreck the spread between companies is wider still. See how much rates go up after an accident.
What Texas lets insurers use to set your rate
Texas allows companies to rate on your driving record, your ZIP code, the car, how much you drive, your prior insurance history, and a credit based insurance score. That score is built from credit data, and it is not the same as your credit score.
Every Texas policy also includes personal injury protection unless you turn it down in writing. It pays medical bills for you and your riders no matter who caused the wreck. Companies must also offer uninsured motorist coverage, which pays when the other driver has none, and you can only decline it in writing. See the Texas Department of Insurance.
Those two coverages are part of why a South Texas quote looks the way it does. Turning them down lowers the bill only by moving the risk onto you.
What actually works
- Compare across companies every two years, and after any change in your life. See the full list of what lowers a premium.
- Ask for each discount by name rather than waiting to be offered one.
- Raise the deductible before you cut liability limits.
- A defensive driving course can remove a ticket in Texas, and a ticket sits on your rate for years.
- Read a first policy closely, since it has traps of its own. See buying car insurance for the first time.
Let us run the comparison
We are independent, so we can quote across companies in one sitting instead of one at a time.
Pull out your current policy page and check your coverage and your deductible, so each quote covers the same thing. Then call our McAllen office at (956) 687 3334, or use the ZIP form on this page.
Common follow-up questions
Does my credit affect my car insurance in Texas?
Texas lets companies use a credit based insurance score as one rating factor. It is built from credit data, it is not the same as your credit score, and it is one input among many.
Will moving a few miles change my rate?
It can. Rates are set by ZIP code, and two ZIP codes next to each other sometimes price differently enough to notice.
Do tickets stay on my rate forever?
No. Most companies look back three to five years. One minor violation usually stops affecting your bill before it leaves your record.
Need a quote?
Enter your ZIP code to get started. Ten questions, about two minutes.
Or call (956) 687 3334, Monday to Friday, 9 AM to 6 PM.
Read next
Buying car insurance for the first time in South Texas
Auto · 5 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.